

Unlocking Equity Across Two Properties: Preserve the First Mortgage and Put Home Equity to Work.
A borrower owned both a primary residence and a rental property, each with significant equity and an existing low-interest first mortgage. Rather than replacing those first mortgages, the borrower used two different second-lien financing solutions to access equity for separate goals.
The Challenge
The borrower wanted to fund home improvements at the primary residence and build an accessory dwelling unit (ADU) on the rental property to generate additional rental income. Refinancing either first mortgage could have meant giving up a favorable existing interest rate.
The Solution
We used different financing approaches to meet the needs of each property:
- Primary Residence: A $150,000 cash-out HELOC provided funds for home improvements.
- Investment Property: A $624,000 closed-end second mortgage (HELOAN) provided cash for ADU construction, with qualification based on the property's debt service coverage rather than personal income.
The Result
The borrower obtained financing for both objectives: improving the primary residence and investing in an ADU intended to create additional rental income. The primary-residence transaction closed in 22 days, and the investment-property transaction closed in 24 days.
The example illustrates how different equity solutions can be tailored to a borrower's property type, goals, and qualification profile.
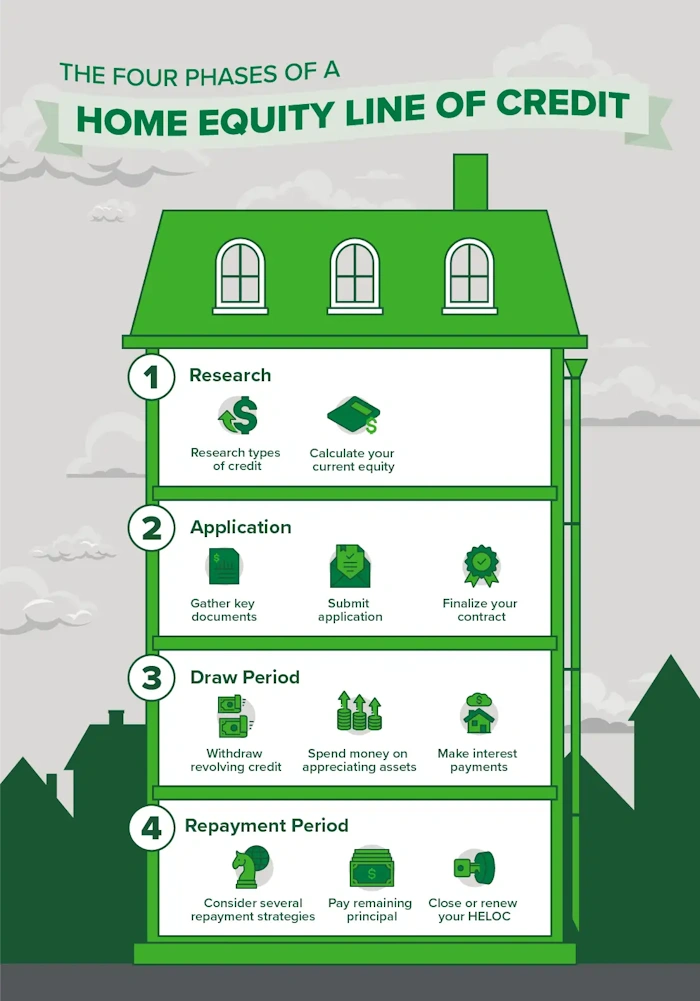
When a HELOC Offers More Flexibility
Ray is a general contractor who owns several investment properties. Over time, he had built substantial equity in two of those properties and wanted to access $150,000 from each to fund property repairs and improvements.
Rather than receive two lump-sum payouts through traditional Home Equity Loans (HELOANs), Ray wanted more flexibility over how and when he accessed the funds.
The Challenge
Ray needed $300,000 for repairs and improvements but didn't want to borrow the entire amount upfront.
The Solution
Two HELOCs provided revolving access to approved funds, allowing him to draw as projects progressed.
The Result
Ray could pay contractors as work was completed and reduce his outstanding balances when cash flow allowed.
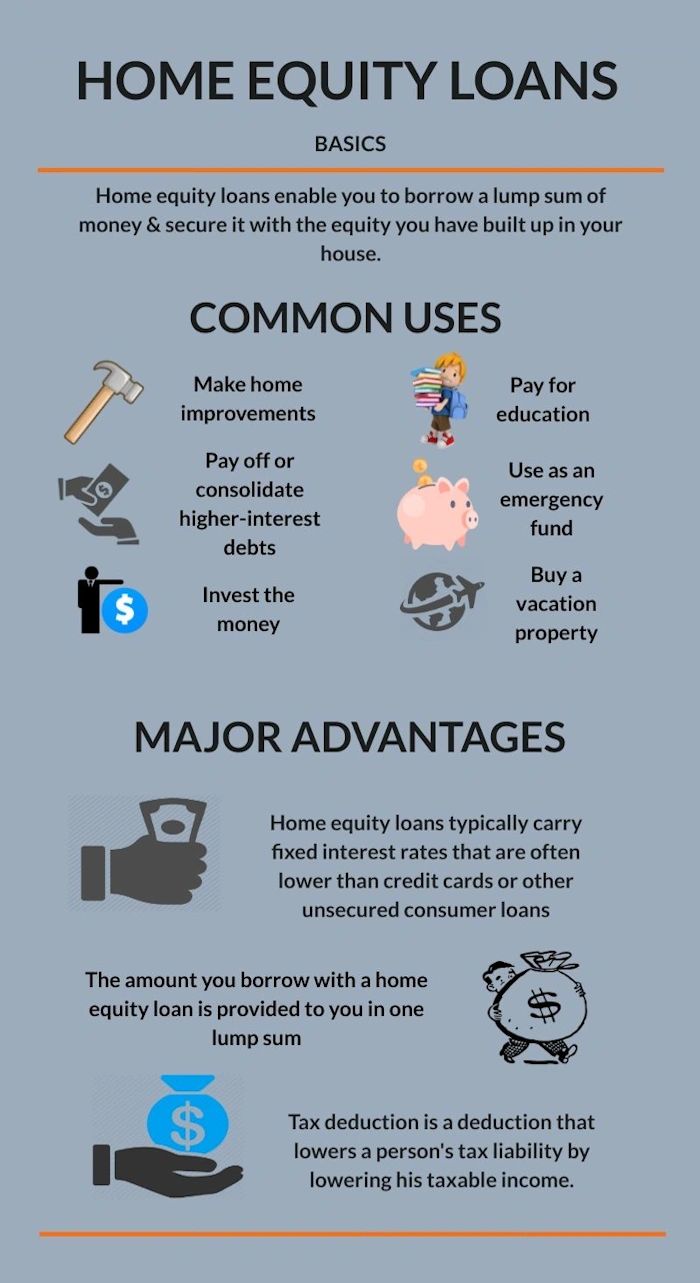
“When a Fixed-Rate HELOAN Makes More Sense
John lives in Montclair, California, and has owned his home for more than 30 years. When he refinanced in 2021, he secured a very low interest rate on his first mortgage. With that favorable rate, replacing his existing mortgage was not an attractive option.
As John approaches retirement, he began exploring ways to create an additional source of income. His backyard was large enough to accommodate an accessory dwelling unit (ADU) of up to 800 square feet. Given the demand for rental housing in his established community, he saw an opportunity to create a rental property that could generate supplemental income during retirement.
The Challenge
John had owned his Montclair, California home for more than 30 years and refinanced in 2021, securing a very favorable first mortgage rate.
As he approached retirement, John wanted to build an approximately 800-square-foot ADU in his backyard to generate supplemental rental income. He wanted to access his home's equity without disturbing his existing first mortgage.
The Solution
We evaluated both a HELOC and a closed-end Home Equity Loan (HELOAN).
John preferred a 30-year fixed-rate HELOAN because he valued predictable payments and long-term stability over the flexibility of a variable-rate credit line.
The structure allowed him to access equity while preserving his existing first mortgage.
The Result
John planned for construction to take approximately nine months. He intended to cover the first 12 months of the new loan payments through his employment income while the ADU was being completed and prepared for rental.
His longer-term goal was for the anticipated rental income to help offset the additional mortgage expense as he transitioned into retirement.